Home Cover Made Clear
Let me show you what dwelling cover, belongings cover and liability actually do, so you can set limits that fit your property.
Explore CoverageInside the walls
Dwelling Cover
Everyday items
Personal Belongings
If a visitor is hurt
Liability Options
Two houses on the same street can need very different cover. Square footage, the age of the wiring and whatever sits in the garage all change the picture, so that is the part I walk through with you first.
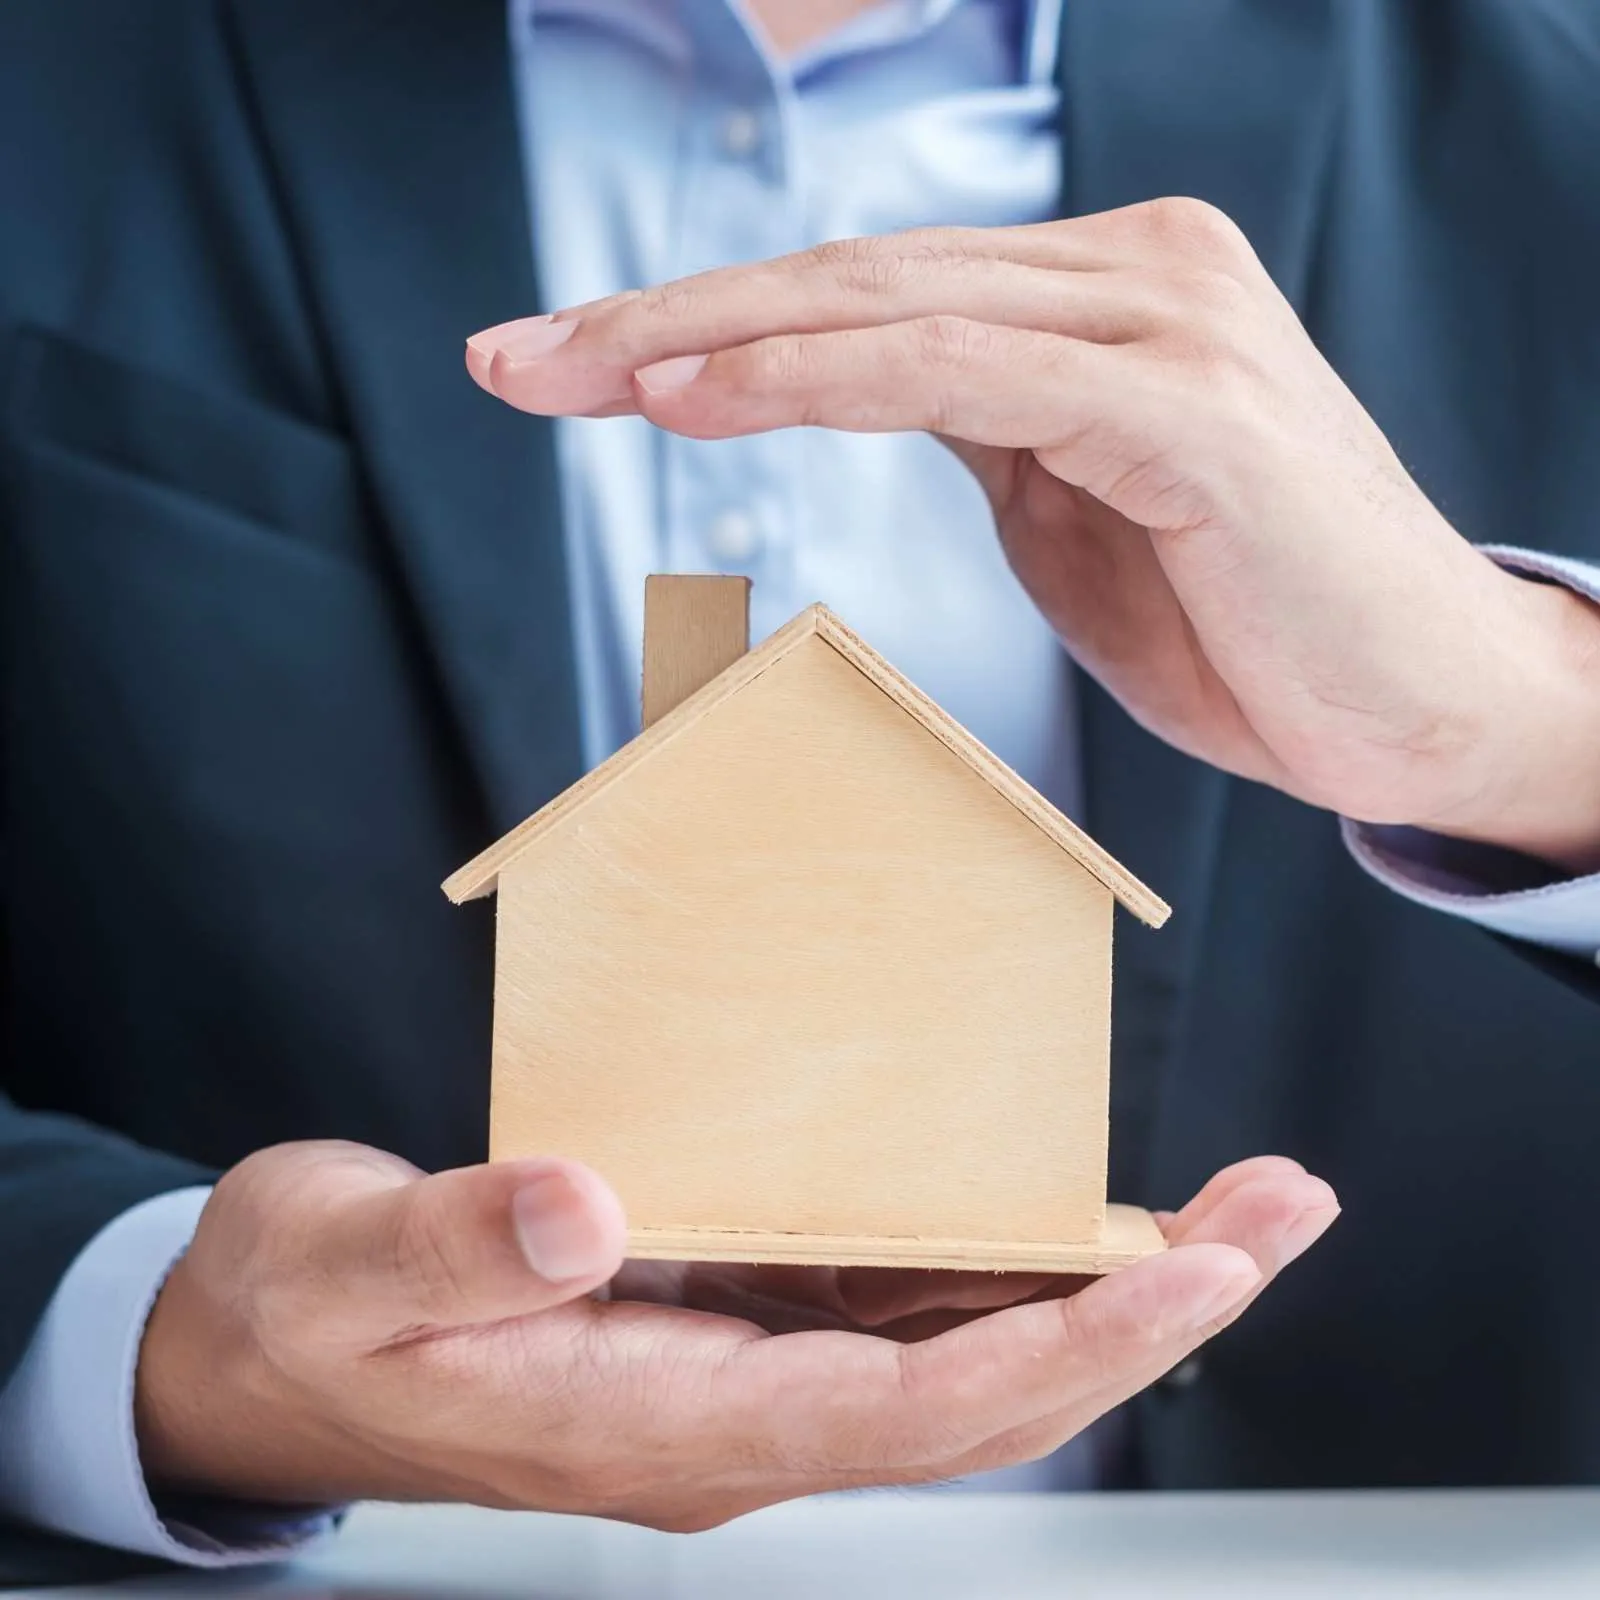
I start here, because this limit is what rebuilds the structure after a covered loss: walls, roof, floors and the frame behind them.
Read MoreFurniture, clothing and electronics stack up quicker than you think, so I count them room by room and list the costly pieces alone.
Read MoreIf someone is hurt while visiting you, this is the part I check first, since it answers the claim and the legal bills behind it.
Read MoreI begin with the building itself: how old it is, how big it is, the shape of the roof, the heating and anything replaced lately.
Then I ask which belongings deserve their own listing, how much liability sits right with you, and what deductible you could pay without strain.
I put the options side by side, read out what each one leaves behind, and you choose with nothing hidden in the footnotes.
Give me a few minutes and I will show you which parts of a home policy touch your property, and what a sensible limit looks like for the way you live in it.
Dana Whitfield
Homeowner
I never knew the belongings limit worked separately from the building limit. Reading through it here made the renewal notice make sense for the first time.
Marlon Ashby
First Time Buyer
The part about rebuild cost versus what I paid for the house cleared up a question I had been carrying around since closing day.
Elise Tanaka
Condo Owner
Going room by room felt like a chore until I saw what the electronics alone came to. That hour changed which limit I picked.
Curtis Nkemelu
Homeowner
Liability was the section I always skipped past. Now it is the first thing I check, since people are in and out of the house all summer.
Bridget Alvarado
Renter
I rent, so I assumed none of this applied to me. Turns out my things and my liability were the two parts worth sorting out.
I get these questions from first time buyers and from owners who have carried the same policy for years, so I keep the answers short.
I break every policy into four parts: the structure, the belongings inside it, liability if a person is hurt, and the extra cost of living somewhere else while repairs run.
It is the slice you pay on a covered claim before the policy pays a cent, so I tell people to pick a figure they could hand over without borrowing.
Build year, roof age, wiring and floor area drive both the price and the payout, so I look for records that quietly fell out of date.
Yes. Household items sit under one limit, and I list the higher value pieces such as rings or cameras separately.
Once a year fits most homes, and I would look again after a renovation, a new roof or any large purchase that now lives indoors.